RBI rate hike has hit borrowers hard, with PNB, Bank of Baroda, and Indian Bank raising their lending rates in response. This change poses challenges for those seeking loans.
Understanding RBI’s Rate Hike
The recent RBI rate hike has sent shockwaves through the financial sector, particularly affecting borrowers across the nation. With the Reserve Bank of India (RBI) increasing the repo rate by 25 basis points, many banks are now forced to reassess their lending rates. This rise in the rate directly impacts the cost of borrowing for individuals and businesses alike.
As banks adjust their rates, borrowers can expect to see changes in their loan repayments. Major institutions like PNB, Bank of Baroda, and Indian Bank have already announced hikes in their lending rates, which will add to the financial burden of those with existing loans.
This decision by the RBI is aimed at curbing inflation, but it also raises concerns for many families and small businesses who rely on loans for their everyday needs. The implications of this RBI rate hike are significant and could lead to challenging financial situations for many borrowers.
In this context, understanding the ripple effects of the rate increase is crucial for managing personal and business finances effectively.
Impact on Borrowers
The recent RBI rate hike has significant implications for borrowers across the country. With the Reserve Bank of India increasing the rates by 25 basis points, financial institutions are compelled to adjust their lending rates accordingly.
In light of this development, many banks have announced an increase in their interest rates, which directly affects borrowers. The following points highlight the impact:
- Increased EMI Payments: Borrowers will face higher equated monthly installments (EMIs) on their loans, making monthly budgeting more challenging.
- Impact on New Loans: Individuals looking to take out new loans will find that the cost of borrowing has risen, which could deter potential homebuyers and personal loan seekers.
- Pressure on Existing Loans: Those with floating rate loans will experience an immediate increase in interest costs, leading to a potential strain on finances.
- Long-term Financial Planning: Borrowers may need to reevaluate their long-term financial strategies in light of the RBI rate hike, considering the ongoing adjustments in lending rates.
As the situation evolves, borrowers will need to stay informed and adapt to these changes in the lending landscape.
What Banks Are Raising Rates?
The recent RBI rate hike has prompted several banks to adjust their lending rates, directly affecting borrowers across the country. As financial institutions respond to the Reserve Bank of India’s decision, many are implementing increases that could lead to higher monthly repayments for customers.
Among the banks that have announced rate hikes are:
- Punjab National Bank (PNB) – Following the RBI’s increase, PNB has adjusted its lending rates by 25 basis points.
- Bank of Baroda – This bank has also raised its lending rates, impacting home and personal loan borrowers.
- Indian Bank – Indian Bank has joined the trend by hiking its rates, reflecting the ripple effect of the RBI rate hike.
The adjustments made by these banks indicate a broader trend, as financial institutions align their policies with the central bank’s monetary policy. Borrowers should be prepared for these changes, which could significantly affect their financial planning.
Future of Lending Rates
The recent RBI rate hike has left many borrowers concerned about the future of lending rates. As banks adjust their interest rates in response to the Reserve Bank of India’s decision, borrowers are likely to feel the repercussions in their monthly payments.
Experts predict that the continued tightening of monetary policy may lead to:
- Increased borrowing costs: With the RBI rate hike, lending rates are expected to rise further, making loans more expensive for individuals and businesses.
- Slower economic growth: Higher interest rates can dampen consumer spending and business investment, potentially stalling economic recovery.
- Shift in lending strategies: Banks may become more cautious in their lending practices, focusing on borrowers with stronger credit profiles.
As the financial landscape shifts, individuals seeking loans should brace for tighter conditions and reassess their financial strategies. The ripple effects of the RBI rate hike will likely influence personal finances for the foreseeable future, underscoring the importance of understanding the evolving lending environment.
Expert Opinions on the Hike
Experts are voicing their concerns regarding the recent RBI rate hike, emphasizing its potential ramifications for borrowers. According to financial analysts, the 25 basis points increase is expected to exacerbate the financial burdens faced by individuals and businesses alike.
Dr. Aditi Sharma, an economist at a leading financial institution, states, “This RBI rate hike will lead to higher lending rates, making it more expensive for borrowers to service their loans. Those with variable interest rates will feel the pinch most acutely.”
Additionally, Mr. Rajeev Kumar, a banking consultant, highlights, “As banks adjust their rates in response to the RBI’s decision, we may see a further tightening of credit, which could slow down economic growth.”
In contrast, Ms. Priya Singh, a financial advisor, mentions, “While the hike may deter some borrowing, it is crucial for maintaining economic stability and controlling inflation.”
Overall, the consensus among experts is clear: the RBI rate hike poses significant challenges for borrowers and the lending landscape.
Advice for Borrowers
As the recent RBI rate hike takes effect, borrowers must take proactive measures to manage their finances. With the central bank’s decision to increase rates, the cost of borrowing is likely to rise significantly, affecting mortgages, personal loans, and other forms of credit.
- Review Existing Loans: Borrowers should carefully examine their current loans and consider refinancing options if they are facing higher interest rates.
- Fixed vs. Floating Rates: Evaluate whether switching to a fixed-rate loan might be beneficial in the current climate, as it could provide stability against future rate hikes.
- Budget Adjustments: Anticipate increased monthly payments and adjust your budget accordingly to avoid financial strain.
- Emergency Fund: Build or bolster an emergency fund to ensure you can cover additional costs that may arise from increased lending rates.
- Consult Financial Advisors: Seeking expert advice can help you navigate the complexities of the current lending environment following the RBI rate hike.
By staying informed and proactive, borrowers can better manage their finances during these challenging times.
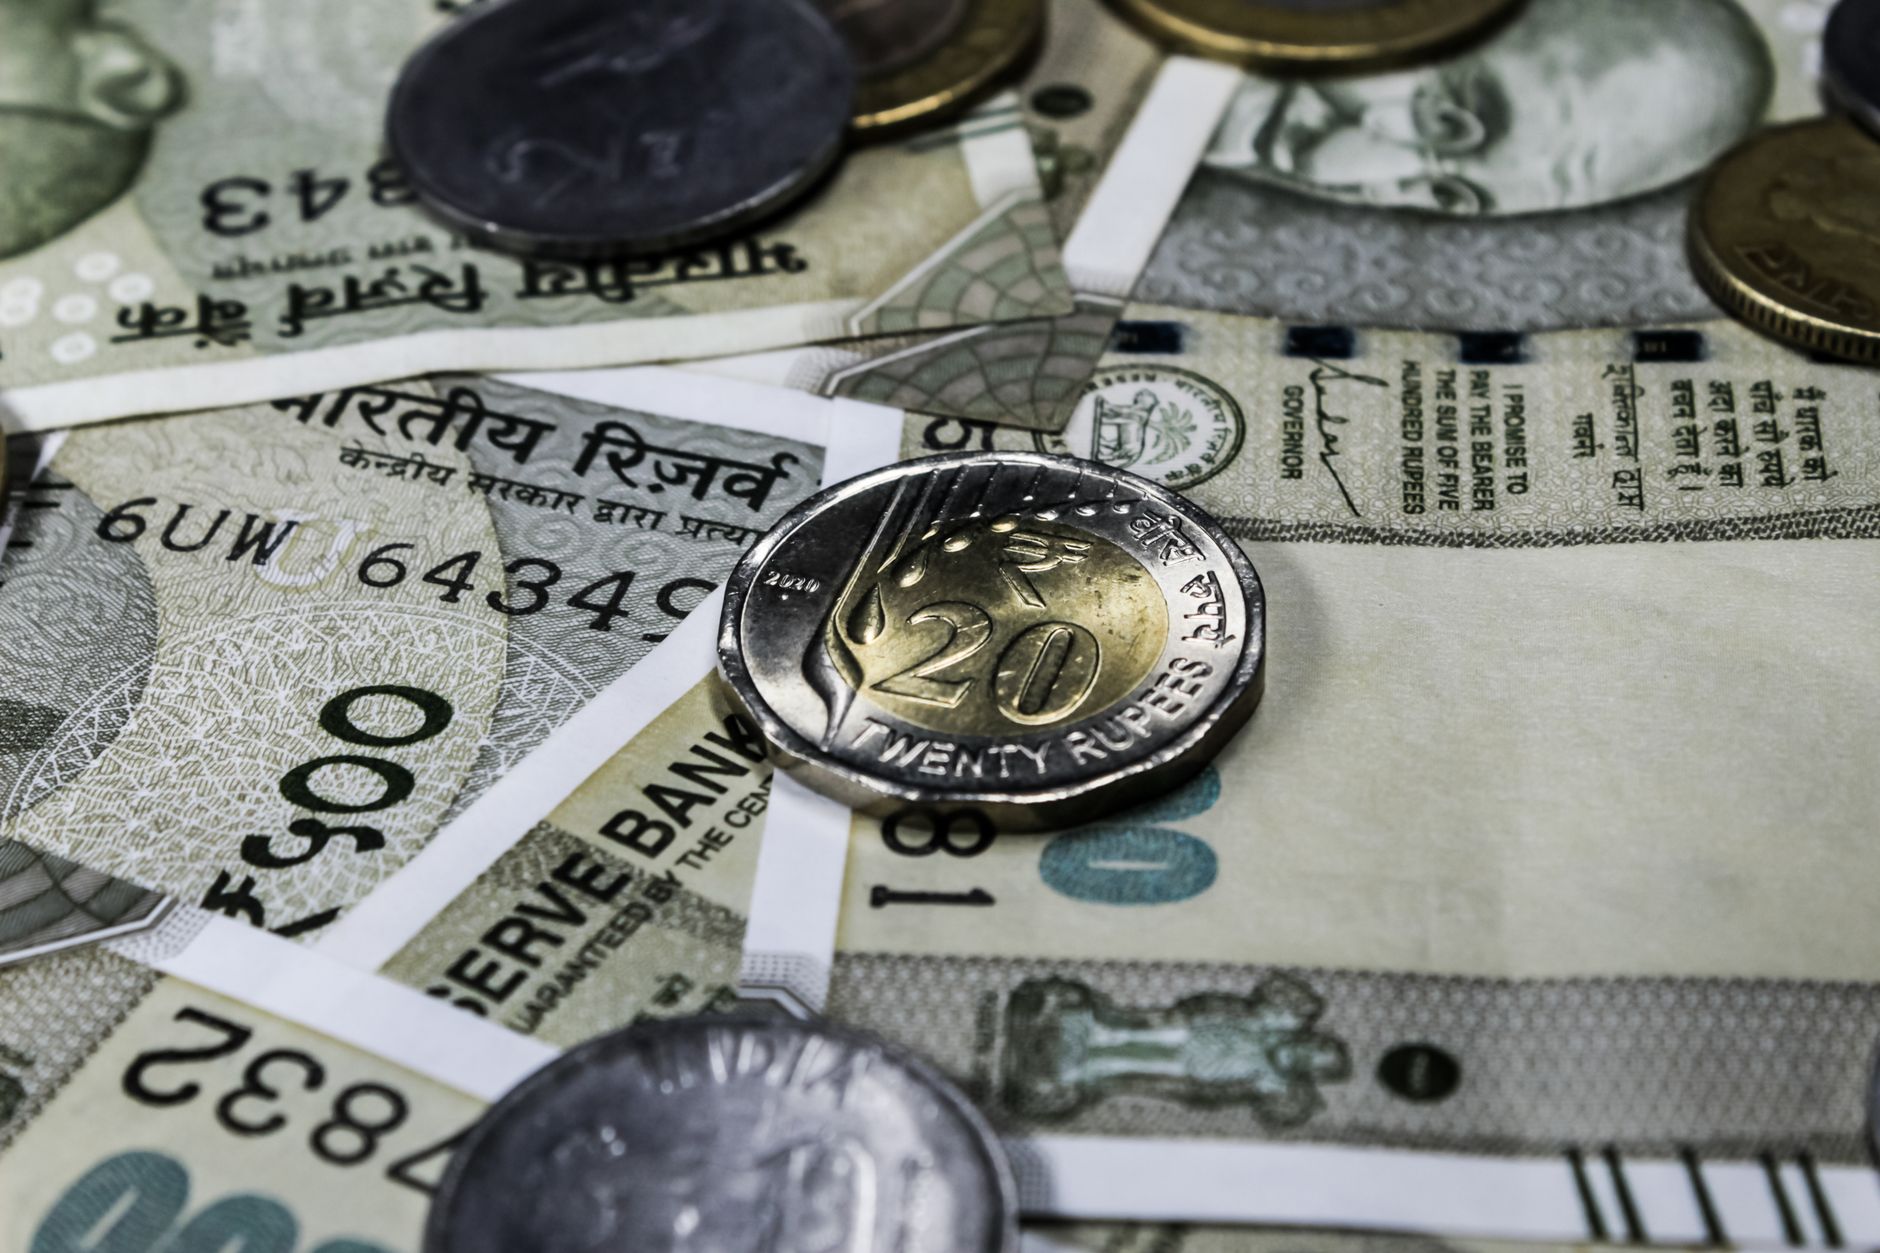
Photo by Ravi Roshan on Pexels